This wire instruction matching card validates critical transfer details for mortgage closing fund disbursements, payroll tax remittances, and commercial property claim payout transfers handled through your Margin Desk folder. Mismatched details can result in delayed fund posting, returned transfers, or misapplied payments that set back closing dates, incur late payroll tax penalties, or hold up claim payout disbursements for property repairs. All entries on this card should be cross-referenced directly with written, verified instructions from the issuing party (closing agent, payroll tax authority, or insurance adjuster) rather than verbal instructions sent via phone or unencrypted email. Keep a printed copy of this completed card in your transfer folder for 7 years for audit and reconciliation purposes.
Routing number verification field
The 9-digit American Bankers Association (ABA) routing number is the core routing identifier for all domestic U.S. wire transfers, and even a single digit error will result in a rejected or misrouted transfer. To complete this field, cross-reference three independent sources before entering the number in your transfer portal: first, the official typed wire instruction document issued directly by the receiving party via a secure encrypted portal, second, the FDIC BankFind tool to confirm the routing number is active and assigned to the named receiving institution, and third, a verbal confirmation with the receiving institution’s dedicated wire department (not a general customer service line) to confirm the number is valid for incoming wire transfers. A common error is using the receiving bank’s ACH routing number instead of its separate wire routing number, as 60% of U.S. banks maintain distinct routing numbers for ACH and wire transactions per industry audit data. Illustrative example: A regional credit union in Illinois uses routing number 071000013 for ACH deposits and 071000028 for incoming wire transfers, so entering the ACH number will result in the wire being returned to your account 3 to 5 business days after submission. Once verified, write the routing number in this field, sign and date the entry to confirm you completed all three verification steps.
Beneficiary name entry box
The beneficiary name field must match the full legal name associated with the receiving bank account exactly, with no nicknames, abbreviations, or omitted entity designations unless explicitly approved by the receiving bank in writing. For mortgage closing transfers, the beneficiary is almost always the full legal name of the title or escrow agency handling the closing, not the individual name of the closing agent assigned to your file. For payroll tax remittances, the beneficiary is the exact legal name of the state or federal tax authority, for example “United States Treasury” rather than “IRS” or “Federal Tax Office”. For commercial property claim payout transfers, the beneficiary must include all named parties on the receiving account, including any lienholders, such as “Maple Street Property Holdings LLC and Northwood Commercial Lending” rather than just “Maple Street Holdings”. Even a missing “LLC”, “Inc.” or “FBO” (for the benefit of) designation will trigger a rejection under federal anti-money laundering rules, as receiving banks are required to validate full account name matches for all incoming wires. If the beneficiary name exceeds the character limit of your transfer portal’s entry box, contact the receiving bank’s wire department to get written confirmation of approved truncation before submitting the transfer.
Intermediary bank routing schedule
Some smaller banks, credit unions, and international receiving institutions use intermediary correspondent banks to process incoming wire transfers, and these details must be entered exactly as listed on official instructions to avoid delays. Do not add intermediary bank details if they are not explicitly included on the official wire instructions you received from the issuing party, as unsolicited intermediary updates are one of the most common indicators of wire fraud. If intermediary details are provided, you must confirm the routing number and legal name of the intermediary with both the issuing party and the receiving bank to ensure the intermediary is an authorized correspondent for the receiving institution. Use the matching card table below to track all verification steps for every field associated with your transfer:
| Field Name | Source Verification 1 (Issuer Official Written Instructions) | Source Verification 2 (Third Party Confirmation) | Verified Checkbox | Notes Field |
|---|---|---|---|---|
| 9-Digit Domestic ABA Wire Routing Number | Cross-reference with typed wire instruction PDF sent directly from closing agent, tax authority, or adjuster via encrypted portal | Confirm routing number matches institution details via FDIC BankFind tool or receiving bank wire department phone call | ☐ | Note if separate ACH routing number is listed to avoid mix-up |
| Beneficiary Full Legal Account Name | Match exact spelling, punctuation, and business entity designations (LLC, Inc, FBO) as written on official instructions | Confirm name matches account registration via verbal confirmation with receiving bank representative | ☐ | Note approved truncation if name exceeds entry box character limit |
| Intermediary Bank Routing Number (if applicable) | Verify intermediary name and routing number are explicitly listed on official instructions, no unsolicited intermediary details are accepted | Confirm intermediary is an authorized correspondent for the receiving bank via receiving bank wire department | ☐ | Note any intermediary processing fees to reconcile final received amount |
| Payment Reference Number | Copy exact alphanumeric reference number as listed on closing disclosure, tax payment voucher, or claim payout cover sheet | Confirm reference number is valid and associated with your transaction via a follow-up email to the issuing party | ☐ | Note if reference number must be formatted with spaces or hyphens for auto-posting |
| Receiving Account Number | Cross-reference last 4 digits of account number with a separate written confirmation from the receiving party (not included in the same wire instruction document to reduce fraud risk) | Confirm last 4 digits of account number match receiving party’s verbal confirmation over a verified phone line | ☐ | Redact full account number on printed copies stored in non-locked folders for security |
| Total Wire Transfer Amount | Match amount exactly to the closing disclosure final cash to close, tax remittance balance due, or approved claim payout amount | Confirm amount matches written confirmation sent to you by your broker, HR desk, or licensed adjuster 24 hours prior to transfer | ☐ | Note any wired fee deductions that are pre-approved by the receiving party |
Intermediary banks typically charge a processing fee between $10 and $35 per transfer, which will be deducted from the total amount sent unless you select to pay fees upfront. Note any approved fee deductions in the notes field of your matching card so you can reconcile any discrepancies between the amount you sent and the amount the receiving party posts to your account. Illustrative example: A $250,000 mortgage closing wire sent through an intermediary that charges a $25 fee will result in $249,975 being received by the title agency, so you must confirm this fee deduction is approved by the closing agent before submitting the transfer to avoid a funding shortfall on closing day.
Payment reference number column
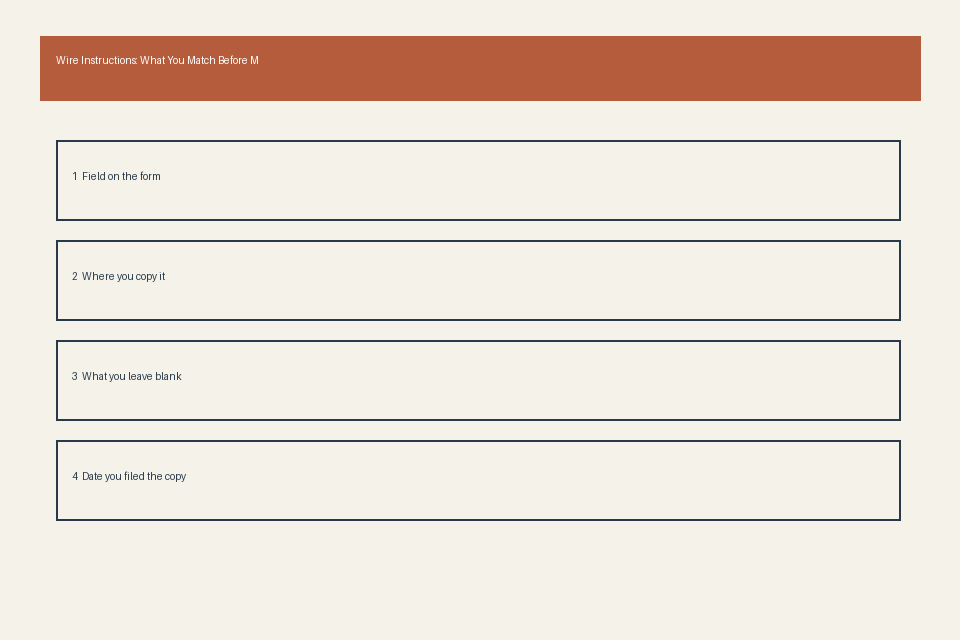
The payment reference number is the unique alphanumeric identifier that tells the receiving party which transaction the incoming wire is associated with, and incorrect or missing reference numbers are the leading cause of delayed payment posting even when routing and account details are correct. For mortgage closing transfers, the reference number is usually your unique closing file number or the full property address formatted exactly as requested on the closing disclosure. For payroll tax remittances, the reference number is your employer identification number (EIN) plus the tax period and form number, for example “12-3456789 Q3 2024 Form 941”. For commercial property claim transfers, the reference number is your assigned claim number plus the property address associated with the claim. Many receiving institutions use auto-posting software that will reject references with incorrect formatting, including missing hyphens, spaces, or special characters, so confirm the required format with the issuing party before entering the reference in your transfer portal. Write the exact reference number on your matching card and keep a copy in your transfer folder so you can provide it to the receiving party if the payment is not posted within 24 hours of submission.
Mismatch escalation routing note
Any discrepancy between your two verification sources for any field on the matching card requires an immediate pause of the wire transfer, no exceptions. Do not make assumptions about which detail is correct, and never proceed with a transfer if any field has not been verified across two independent sources. Escalate mismatches to the appropriate party based on your transfer type: for mortgage closing transfers, escalate to your closing agent and licensed mortgage broker; for payroll tax transfers, escalate to your HR desk and licensed tax preparer; for commercial property claim transfers, escalate to your assigned insurance adjuster and licensed property manager. Document all escalation communications in writing, including the date, time, full name of the representative you spoke to, and final resolution, and store these records in your transfer folder. Your Margin Desk folder has a dedicated tab for escalation documentation, so you can store all mismatch resolution records alongside your completed matching card for easy access during audits. If you cannot resolve the mismatch within 24 hours of your scheduled transfer date, reschedule the transfer to avoid the risk of sending funds to the wrong account.
Before submitting your next wire transfer, print a copy of the matching card table above, complete all verification steps for each field, and file the signed, completed card in your wire transfer folder before initiating the payment.