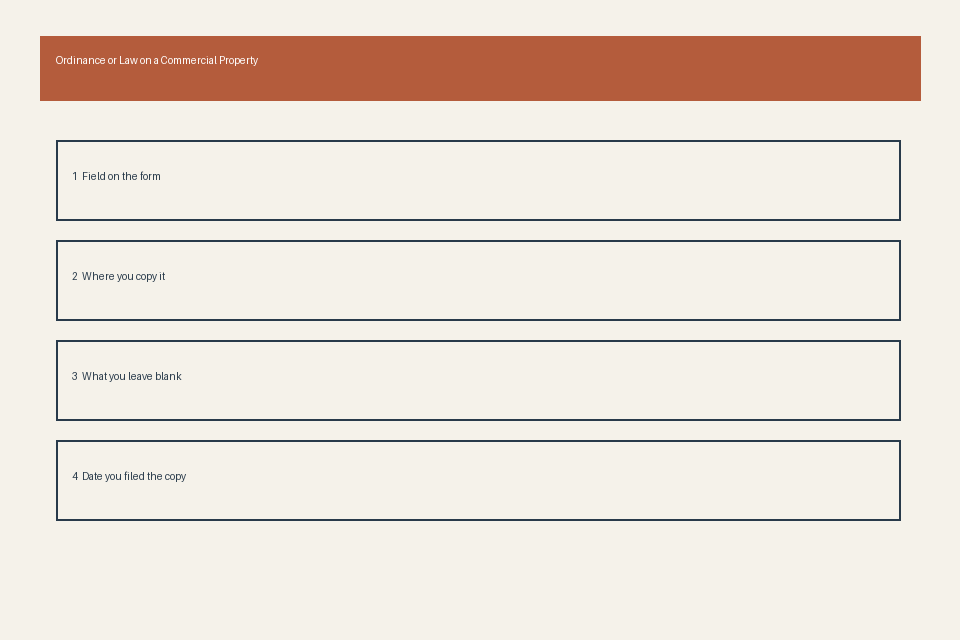
The ordinance or law field card catalogs coverage details for commercial property claims tied to local building code mandates. It is a supplementary document kept in your core commercial property claim file folder, designed to standardize entries so you can easily cross-reference coverage terms, exclusion carveouts, and proof requirements when submitting code-related claims to your carrier. This page is for educational purposes only; always confirm all coverage details with your licensed insurance broker or policy issuer, as no content here binds coverage or determines claim eligibility.
Coverage A Column Entries for Mandatory Building Upgrade Cost Calculations
Coverage A on commercial property forms refers to building structure coverage, and the dedicated columns on the ordinance or law field card separate standard repair costs from costs incurred solely to meet current local building codes, which are not covered under standard Coverage A without an ordinance or law endorsement. The four core columns to complete for each required upgrade are: upgrade description, official local code citation, itemized cost estimate, and policy-covered percentage of cost. You should only complete these columns after receiving written confirmation from your local building department that the upgrade is mandatory following your specific loss, not based on verbal guidance from contractors or adjusters. Illustrative example: If your 1998 12,000 square foot retail building sustains partial fire damage to 40% of its interior, and your local 2018 fire code requires full sprinkler installation for any building over 10,000 square feet undergoing repairs affecting more than 30% of its structure, you would list “Full building sprinkler system installation” in the upgrade description column, cite the specific section of the 2018 local fire code, log the $72,000 itemized estimate from a licensed fire protection contractor, and note the 80% coverage outlined in your policy’s ordinance or law endorsement, for a covered cost entry of $57,600. Do not include costs for upgrades that are not explicitly required by code, such as optional energy efficiency improvements, as these will not be eligible for reimbursement under your ordinance or law coverage.
Claim Adjustment Box Markings for Partial Loss Ordinance Compliance
The lower-left section of the ordinance or law field card includes four pre-printed checkboxes that align with standard insurance carrier adjustment workflows for partial loss claims. You should only mark these boxes after receiving written documentation from your assigned claim adjuster and local code official, as incorrect markings can lead to unnecessary delays in claim processing. The first checkbox, “Loss limited to building elements not up to current code”, applies when the only damaged portions of your building were already out of compliance with current code, and no additional upgrades are required for undamaged portions. The second checkbox, “Partial loss triggers mandatory full upgrade requirements”, applies when a partial loss requires you to upgrade undamaged portions of the building to meet current code, such as a partial roof loss requiring full roof replacement to meet current wind load standards. The third checkbox, “Pre-loss code violations disclosed at policy inception”, applies only if you notified your carrier of existing code violations when you purchased or renewed your policy, and have written confirmation of that disclosure. The fourth checkbox, “Upgrade costs exceed standard Coverage A damaged portion limits”, applies when the total cost of required code upgrades is higher than the Coverage A limit allocated for the damaged portion of your building, which will require you to draw on your separate ordinance or law coverage limit. All marked boxes should be accompanied by a short note citing the date and source of the documentation that supports the marking, such as “Adjuster report dated 10/12/2024” next to the second checkbox.
Exclusion Schedule Annotations for Pre-Existing Code Violation Claims
Nearly all standard ordinance or law endorsements exclude coverage for costs to repair code violations that existed before the covered loss occurred, unless you have a specific written carveout from your carrier. The back of the ordinance or law field card includes a dedicated section for you to transcribe relevant exclusion language directly from your policy’s official schedule, plus space for annotations of any exceptions you believe apply to your claim. For example, if you had a pre-existing ADA access ramp violation that you were in the process of correcting when a vehicle crashed into your storefront, you would transcribe the policy language excluding pre-existing violation coverage, then add an annotation noting that you submitted proof of a pending ramp construction permit to your carrier on 9/18/2024, along with a copy of the permit application and signed contractor bid. As a reminder from Margin Desk, all annotations should be dated and signed by the person filing the claim to create a clear paper trail for your file, and you should never modify or omit exclusion language from your transcription, as this can be considered misrepresentation during claim review. If you are unsure whether a pre-existing condition qualifies for an exception, consult a licensed insurance professional before submitting your claim.
Supporting Documentation Folder Contents for Local Code Change Proof
All ordinance or law claims require a standard set of supporting documents to prove that upgrades are mandatory, covered under your policy, and priced fairly. The table below outlines the core fields of the ordinance or law field card, the required supporting documents for each field, their recommended storage location in your claim folder, and a tracking column for verification status:
| Field Card Field | Required Document | Storage Location in Claim Folder | Verification Status |
|---|---|---|---|
| Code Change Effective Date | Local building department official code update bulletin, stamped with department seal | Subfolder 2 (Code Compliance Proof) | [ ] Unsubmitted [ ] Submitted [ ] Confirmed by Carrier |
| Mandatory Upgrade Requirement | Licensed local code official written post-loss assessment, explicitly stating the upgrade is required for occupancy post-repair | Subfolder 2 (Code Compliance Proof) | [ ] Unsubmitted [ ] Submitted [ ] Confirmed by Carrier |
| Upgrade Cost Estimate | Licensed general contractor itemized bid, separating standard repair costs from code-specific upgrade costs | Subfolder 3 (Repair Cost Estimates) | [ ] Unsubmitted [ ] Submitted [ ] Confirmed by Carrier |
| Pre-Loss Code Compliance Proof | Most recent Certificate of Occupancy, plus all annual inspection records from the 5 years prior to the loss | Subfolder 1 (Pre-Loss Property Records) | [ ] Unsubmitted [ ] Submitted [ ] Confirmed by Carrier |
| Ordinance or Law Coverage Limit Endorsement | Certified copy of your policy declarations page, plus the full text of your ordinance or law endorsement addendum | Subfolder 4 (Policy Documents) | [ ] Unsubmitted [ ] Submitted [ ] Confirmed by Carrier |
All documents should be dated within 90 days of the loss date where applicable, and you should keep both a physical copy in your claim folder and a password-protected digital copy for off-site access. If any document is not available through standard public records requests, you can submit a written request to your local building department for a certified letter confirming the relevant code details, which will be accepted as a substitute for the original document.
Third-Party Verification Letter Requirements for Post-Damage Building Assessments
To avoid conflicts of interest, nearly all insurance carriers require a third-party verification letter from an independent, state-licensed code official or building consultant before approving ordinance or law coverage payouts. This letter must not be written by your regular repair contractor, your in-house property manager, or your assigned insurance adjuster, to ensure unbiased assessment of the required upgrades. The letter must include four core pieces of information to be considered valid: first, the specific, numbered section of the local building code that requires the proposed upgrade; second, a clear statement that the upgrade would not be mandatory if the covered loss had not occurred; third, confirmation that the building was fully compliant with all codes in effect at the time of its original construction, or that any pre-existing violations were previously disclosed to the carrier; and fourth, an independent, itemized cost estimate for the required upgrade, aligned with local market construction rates. Illustrative example: A third-party code consultant’s letter stating that your 2005 suburban office building’s electrical system must be fully upgraded to 2023 National Electrical Code standards following a lightning strike that damaged 30% of the existing wiring, and that local code requires full electrical upgrades for any repair affecting more than 25% of a building’s electrical system, will meet carrier requirements for verification. You should attach a copy of the third party’s current state license to the back of the letter before submitting it to your carrier, and keep a signed copy in your claim folder for your records.
Print a blank copy of the ordinance or law field card and add it to your commercial property policy folder today so you can begin filling it out immediately if you experience a covered loss that triggers mandatory code upgrades.